Non-rated / Industrial Estates / IJ / Click here for full PDF version
A uthor(s): Aurelia Barus ; Belva Monica
- continues to see robust data center demand, with 19ha of presales in 1H26 and c.85ha of remaining land inquiries.
- It is converting additional landbank from commercial and residential to industrial use to meet demand, which we view positively.
- Despite a lower NAV from landbank conversion to industrial, faster monetization could provide dividend upside.
Plenty data center demand; more industrial landbank on the way
currently has 85ha of land inquiries, primarily from the data center sector, comprising of 5-6 clients, with a mix of new and existing tenants seeking expansion. Meanwhile, its available industrial landbank stood at only 60ha as of 1H26, although it still owns 357ha of commercial and 164ha of residential landbank. Based on our discussion with management, has started converting additional landbank into industrial land since end-FY25, although the size has yet to be disclosed. If realized, this should enable to cater to existing inquiries and potential future demand.
Higher power supply visible as demand rises
's existing data center cluster spans 300ha+. Future data center development may expand beyond the existing cluster. PLN currently provides 1GW of power supply for data center use in the area, of which only c.25% is utilized, with only 5-6 players currently already in operation, out of 15-16 tenants. Based on our discussion with , additional power supply is expected to become available as demand rises.
Strong land presales in 1H26 with rising ASP
In 1H26, land presales reached Rp1.15tr (+99% yoy), or 55% of its FY26F target of Rp2.1tr, covering 19ha and primarily driven by data center demand. As of Jul26, asking prices for data center/other industrial land reached Rp4.6/3.8mn, up 23/13% yoy, driven by stronger demand.
Faster landbank monetization supports dividend upside
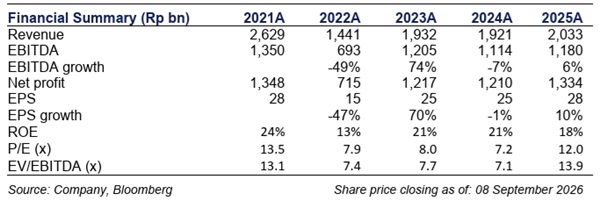
Converting additional landbank to industrial use may lower NAV, as industrial land prices are 43/34% lower than commercial/residential land prices. (Fig. 9) However, we view this positively as it should accelerate landbank monetization. Historically, has paid special dividends following large land presales in the subsequent year (Fig. 8). With Rp2.1tr cash, zero debt, and a historically strong 48-204% dividend payout ratio in 2019-26, we see the potential for higher dividends. currently trades at a 66% discount to NAV and1.3x P/BV FY26F.
Sumber : IPS