Non-rated / Construction / IJ / Click here for full PDF version
A uthor(s): Aurelia Barus ; Belva Monica
- 1H26 pipeline came at Rp17tr (+93% yoy), of which 34% came from data center, positioning as a beneficiary of the data center boom.
- In 1H26, both operational and financial metrics came above targets; FY26F earnings could also exceed target, backed by a higher GPM.
- It maintains its robust balance sheet, with a strong dividend payout ratio and attractive dividend yield.
Robust pipeline growth, led by data center demand
Construction demand remained strong, with the total pipeline reaching Rp17.2tr as of 1H26 (vs. Rp11tr in FY25), comprising 34% data centers, 28% hospitality, 18% industrial, and the remainder as shown in Fig. 3. Based on our latest discussion with the company, the c.Rp5.8tr data center pipeline comprises of five projects, with capacities both below and above 100MW, backed by a mix of local and foreign project owners. This further reinforces 's position as a key beneficiary of the data center boom.
Strong 1H26 operational and financial metrics
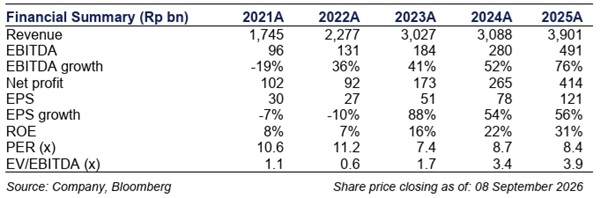
In 1H26, new signed contracts reached Rp2.8tr (+12% yoy; 70% of target), revenue Rp2.1tr (+23% yoy; 53% of FY26F target), GPM after JO 22.65%, and net profit Rp270bn (+54% yoy; 68% of FY26F target). GPM before JO declined to 17.7% from 19.3% in FY25, reflecting higher material costs amid IDR weakness. Despite this, GPM after JO improved to 22.7% from 20.2%, driven by 24% yoy growth in JO profit in 1H26.
Robust 2H26F outlook, with the potential to exceed its internal target
Despite strong 1H26 delivery, maintains a conservative FY26/27F targets of Rp4tr (-43%/flat yoy) in new signed contracts, Rp3.9tr/Rp3.5tr (flat/-10% yoy) in revenue; and Rp400bn p.a. (flat yoy) in net profit. Management expects 2H26F revenue and margins to remain broadly in line with 1H26, with higher costs partly offset by ample JO projects carryover. We believe this could drive FY26F earnings to be above guidance. As of 1H26, had c.Rp6.6tr of non-JO contracts carryover, sufficient to support FY27F revenue.
Strong dividend payout and attractive dividend yields
guides for Rp25bn of normal capex in FY26F and maintains a strong balance sheet, with zero debt and Rp865bn of cash, providing ample capacity for dividends. Historically, has maintained a 73-96% payout ratio, translating into a dividend yield of c.2-7%. The stock currently trades at 11.1x 12M forward P/E, based on Bloomberg consensus, at -1 below standard deviations to its long-term mean.
Sumber : IPS