Sector Update / Telecommunications / Click here for full PDF version
Author(s): Aurelia Barus ; Belva Monica
- AI-driven demand positions Indonesia for the next APAC data center growth wave.
- Power availability is the key bottleneck, with Greater Jakarta and Batam are best positioned near term.
- Economics remain viable despite softer rents and potentially higher power costs; , , , and are our preferred proxy.
AI is accelerating global data center demand, positioning Indonesia for the next APAC growth wave
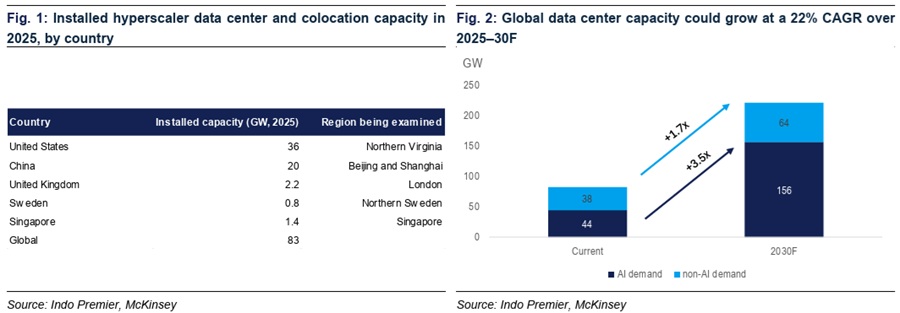
Global data center demand is expected to rise from 82GW in 2025 to c.220GW by 2030F, with AI accounting for c.70%. As inference workloads grow, demand should increasingly favor metro locations with strong fiber, low latency and reliable power. APAC is benefiting, with Indonesia among emerging hubs gaining share as established markets face capacity constraints. Indonesia's operational IT capacity has reached c.580MW in 1H26, with a multi-GW project pipeline, supporting potential market capacity of 3GW+ by 2030F.
Power availability, rather than generation capacity, is the key bottleneck
In FY25, Indonesia has c.9GW of excess generation capacity, mainly in Java and Sumatra, but site-level power connections can take 3-12+ months. PLN's RUPTL 2025-34 adds 69.5GW of generation/storage and 47,758 ckm of transmission, although major inter-island projects are only targeted toward 2031. Greater Jakarta ranks first for readiness, followed by Batam and West/Central Java, with Bintan and East Kalimantan as the next-wave opportunities. Sulawesi remains longer-term given higher seismic risk and a less-developed power and DC ecosystem.
Indonesia's data center economics remain attractive despite softer rents
APAC and Indonesian rental rates have moderated as new capacity comes online, although industry checks suggest Indonesian rates may have bottomed and started to recover. (Fig 15) While potential PLN tariff hikes could add pressure, Indonesia's electricity costs remain competitive with Johor and Singapore. At US$90-200/kW/month hyperscale and US$250-400/kW/month colocation rates, with US$7mn-10mn/MW investment costs, our sensitivity analysis indicates median project IRRs of 11-14% and 20-28%, respectively. We remain constructive, with rental rates and electricity costs as key risks to monitor. (Fig 17)
Multiple proxies to data center theme
We see multiple sectors as proxies for the theme, including industrial estates ( > ), power utilities (), contractors (), AI ecosystem (, IFT), fiber plays (), and data center players (, ). also offers exposure to data centers and fiber infrastructure. Among industrial estate names, is our preferred pick among industrial estate players for this theme, given its strong data center inquiries, sufficient power infrastructure, and potential for additional industrial landbank to support faster monetization. We like , , , and , given clearer monetization potential from rising data center demand, while valuations remain undemanding. Other players with potential future data center expansions include , , and .
Sumber : IPS